Most guides to invoice software for electricians describe software in general: make a PDF, email it, mark it paid. That is not where electrical invoicing actually goes wrong. It goes wrong at the labour and materials split, at CIS deductions, at the domestic reverse charge, at variations nobody wrote down, and at retention nobody ever invoiced for. This guide covers those, then what they mean for the system you choose.
What makes an electrician’s invoice different
The legal minimum for a UK invoice is the same whatever your trade: the word “invoice”, a unique sequential number, your name and address, the customer’s name and address, the date of issue and supply, a clear description of what is being charged, the amount due and how to pay. We cover that in full in what to include on an invoice in the UK.
What is different about electrical work is the number of parties who can hold up payment for reasons that have nothing to do with the quality of the work. A main contractor wants a labour and materials split so they can calculate a CIS deduction. A landlord’s managing agent wants a certificate reference before they will release funds. A commercial client’s quantity surveyor wants variations priced separately from the original scope. A domestic customer wants to understand why a “quick” job needed a new circuit. Every one of those is an invoicing problem, not an electrical one.
An invoice that answers those questions before they are asked gets paid on the terms you set. One that does not sits in somebody’s queue while they work out what to do with it, which is where most of the gap between your payment terms and your actual payment times comes from.
Labour and materials belong on separate lines
This is the single most consequential formatting decision on an electrical invoice, and the reason is money rather than tidiness.
Under the Construction Industry Scheme, a contractor paying a subcontractor deducts tax from the labour element only. Materials you have paid for are excluded from the calculation, as is VAT. If your invoice presents one combined figure for “electrical works”, the contractor has nothing to work from. In practice they will either come back to you and hold the payment while they wait, or apply the deduction to the whole amount and leave you to recover the difference through your own tax return months later.
The fix costs nothing at the point of invoicing and is worth real cash flow. Show labour, materials and any plant or equipment hire as separate lines, with the materials at what you actually paid plus any markup identified as its own line if you apply one.
- Labour, described by what was done, not by hours alone
- Materials, listed or summarised, at cost
- Any markup on materials, if you charge it, as a visible line
- Plant, access equipment or specialist tool hire
- Subcontracted work you have engaged and are passing on
A note on tax detail. CIS deduction rates, the reverse charge conditions and VAT thresholds are set by HMRC and do change. The structure described here is stable, but confirm current rates and your own status with HMRC or your accountant before you rely on them. This is a guide to invoicing practice, not tax advice.
CIS deductions and what your invoice has to make possible
If you subcontract to main contractors, CIS shapes your cash flow more than your day rate does. The contractor deducts tax at source from the labour element and pays it to HMRC on your behalf. The rate depends on your registration status: registered subcontractors are deducted at the standard rate, unregistered subcontractors are deducted at the higher rate, and those with gross payment status are paid in full and settle their own tax.
The practical consequences for your invoice are specific:
- The labour and materials split must be unambiguous, because it determines the deductible amount
- VAT sits outside the CIS calculation, so a VAT-inclusive total obscures the figure the contractor needs
- Your invoice number needs to match what appears on the payment and deduction statement the contractor issues you, or reconciling the year is painful
- You need to be able to find, months later, what a given deduction related to
That last point is where a spreadsheet stops coping. Deductions arrive as statements from several contractors on different cycles, and matching them back to the right invoice at the end of the year is a genuine chore if the invoices are individual files in a folder. Keeping invoices in one system with the client, job and status attached is what makes that reconciliation a lookup rather than an excavation.
The VAT domestic reverse charge
Since March 2021, construction services between VAT-registered businesses in the CIS chain have been subject to the domestic reverse charge, and it catches a lot of electricians out because it changes what your invoice says and what you get paid.
Broadly, the reverse charge applies where all of the following are true:
- Both you and your customer are VAT registered
- Both are registered for CIS
- The supply is a construction service covered by CIS, at standard or reduced rate
- Your customer is not an “end user” or intermediary who has told you so in writing
When it applies, you do not charge VAT. The customer accounts for it to HMRC themselves. Your invoice still has to make that explicit: it must state that the reverse charge applies and show the VAT rate or the VAT amount the customer needs to account for, while excluding it from the total payable to you. Wording along the lines of “Domestic reverse charge: customer to account to HMRC for the VAT” is what most contractors expect to see.
When it does not apply, which includes all your work direct for domestic householders and any customer who has confirmed end user status in writing, you invoice normally and charge VAT as usual.
The reason this matters for software selection is that you are running two invoice formats side by side, often in the same week, and picking the wrong one either under-collects VAT or hands HMRC a problem. If your invoicing is a duplicated spreadsheet, the wrong template gets used eventually. What helps is being able to hold the treatment against the client rather than remembering it per invoice.
Certificates, Part P and the paperwork trail
Electrical work produces certification that no other trade’s invoicing has to account for, and the invoice is where the two records meet.
| Document | Typically issued for | On the invoice |
|---|---|---|
| Electrical Installation Certificate (EIC) | New installations, rewires, new circuits, consumer unit replacement | Certificate reference against the line it covers |
| Minor Electrical Installation Works Certificate | Additions and alterations not involving a new circuit | Reference, plus the circuit or board affected |
| Electrical Installation Condition Report (EICR) | Periodic inspection, landlord and pre-purchase checks | Report reference; remedial work invoiced separately |
| Building control notification | Part P notifiable work in dwellings (England and Wales) | Note that notification has been made, and by which scheme |
Two habits pay for themselves here. The first is quoting the certificate or report reference on the invoice line it relates to, because for landlords and agents that reference is the evidence their compliance file needs, and its absence is a common reason an invoice sits unpaid without anyone telling you why.
The second is invoicing remedial work separately from the inspection that found it. An EICR and the C1 and C2 remedials arising from it are different pieces of work, often authorised by different people and sometimes paid from different budgets. Combining them into a single line is how a straightforward inspection fee ends up held hostage to a dispute about remedial pricing.
Day rate, price work and schedules of rates
Electricians rarely bill one way, and each model fails differently on an invoice.
| Model | Where it is used | What the invoice has to show |
|---|---|---|
| Call-out plus hourly | Reactive domestic and small commercial faults | Call-out as its own line, then hours at the stated rate, so the customer can see the minimum charge was not arbitrary |
| Day rate | Subcontract labour, site work | Dates attended and the rate, because a contractor checks days against their own site records before paying |
| Fixed price / price work | Rewires, consumer unit changes, quoted installations | The agreed price referencing the quote number, with variations priced on their own lines |
| Schedule of rates | Framework and maintenance contracts | The rate code alongside each item, since their system reconciles against the schedule, not your description |
| Planned maintenance | Commercial contracts, periodic inspection agreements | The period covered and the sites included, with reactive work billed separately |
The recurring failure is mixing models on one invoice without saying so: a fixed price for the quoted work, plus hours for something extra, all merged into a single figure. The customer cannot check it, so they query it, and the whole invoice waits while one line gets resolved.
Variations: the money most electricians lose
More electrical income is lost to unpriced variations than to bad debt. The pattern is familiar: the job is quoted, work starts, something is found behind the plasterboard or asked for on the day, it gets done because it is quicker than stopping, and it is never written down at a price anyone agreed.
At invoicing, you either absorb it or you raise it for the first time in an invoice, which is the worst possible moment to introduce a number. The customer experiences it as a surprise charge rather than as work they asked for.
The habit that fixes it is confirming the variation in writing before doing it, even briefly, and then invoicing it as its own clearly labelled line against the original quote rather than folding it into the total. We go through this in detail in how to invoice electrical work when the scope changes.
Retention on commercial work
On commercial and construction contracts, a percentage of each payment is commonly held back as retention, typically released in two stages: part at practical completion, and the balance at the end of the defects liability period, often a year later.
Retention is lost far more often through administration than through dispute. Nobody invoices for it, because by the time it falls due the job is long finished and out of mind. Two things prevent that:
- Show retention as a visible deduction line on the original invoice, with the percentage stated, so the gross value and the amount payable now are both on record
- Record the release dates when the invoice is raised, not when you remember, so the claim exists somewhere other than your memory
If you are carrying retention across several contracts, that outstanding balance is real money you have earned. Our guide to the aged debtors report covers keeping sight of balances that age past the point where anyone is chasing them.
What to actually look for in the software
Given all of the above, the criteria that matter for an electrical business are narrower and more specific than a generic feature list suggests.
- Line-level invoicing that makes a labour, materials and plant split natural rather than a workaround
- Per-client settings, so a contractor on the reverse charge and a domestic customer are not one careless template choice apart
- A free-text reference against a line, for certificate and quote numbers
- Sequential invoice numbering you cannot accidentally reuse, which a spreadsheet cannot promise
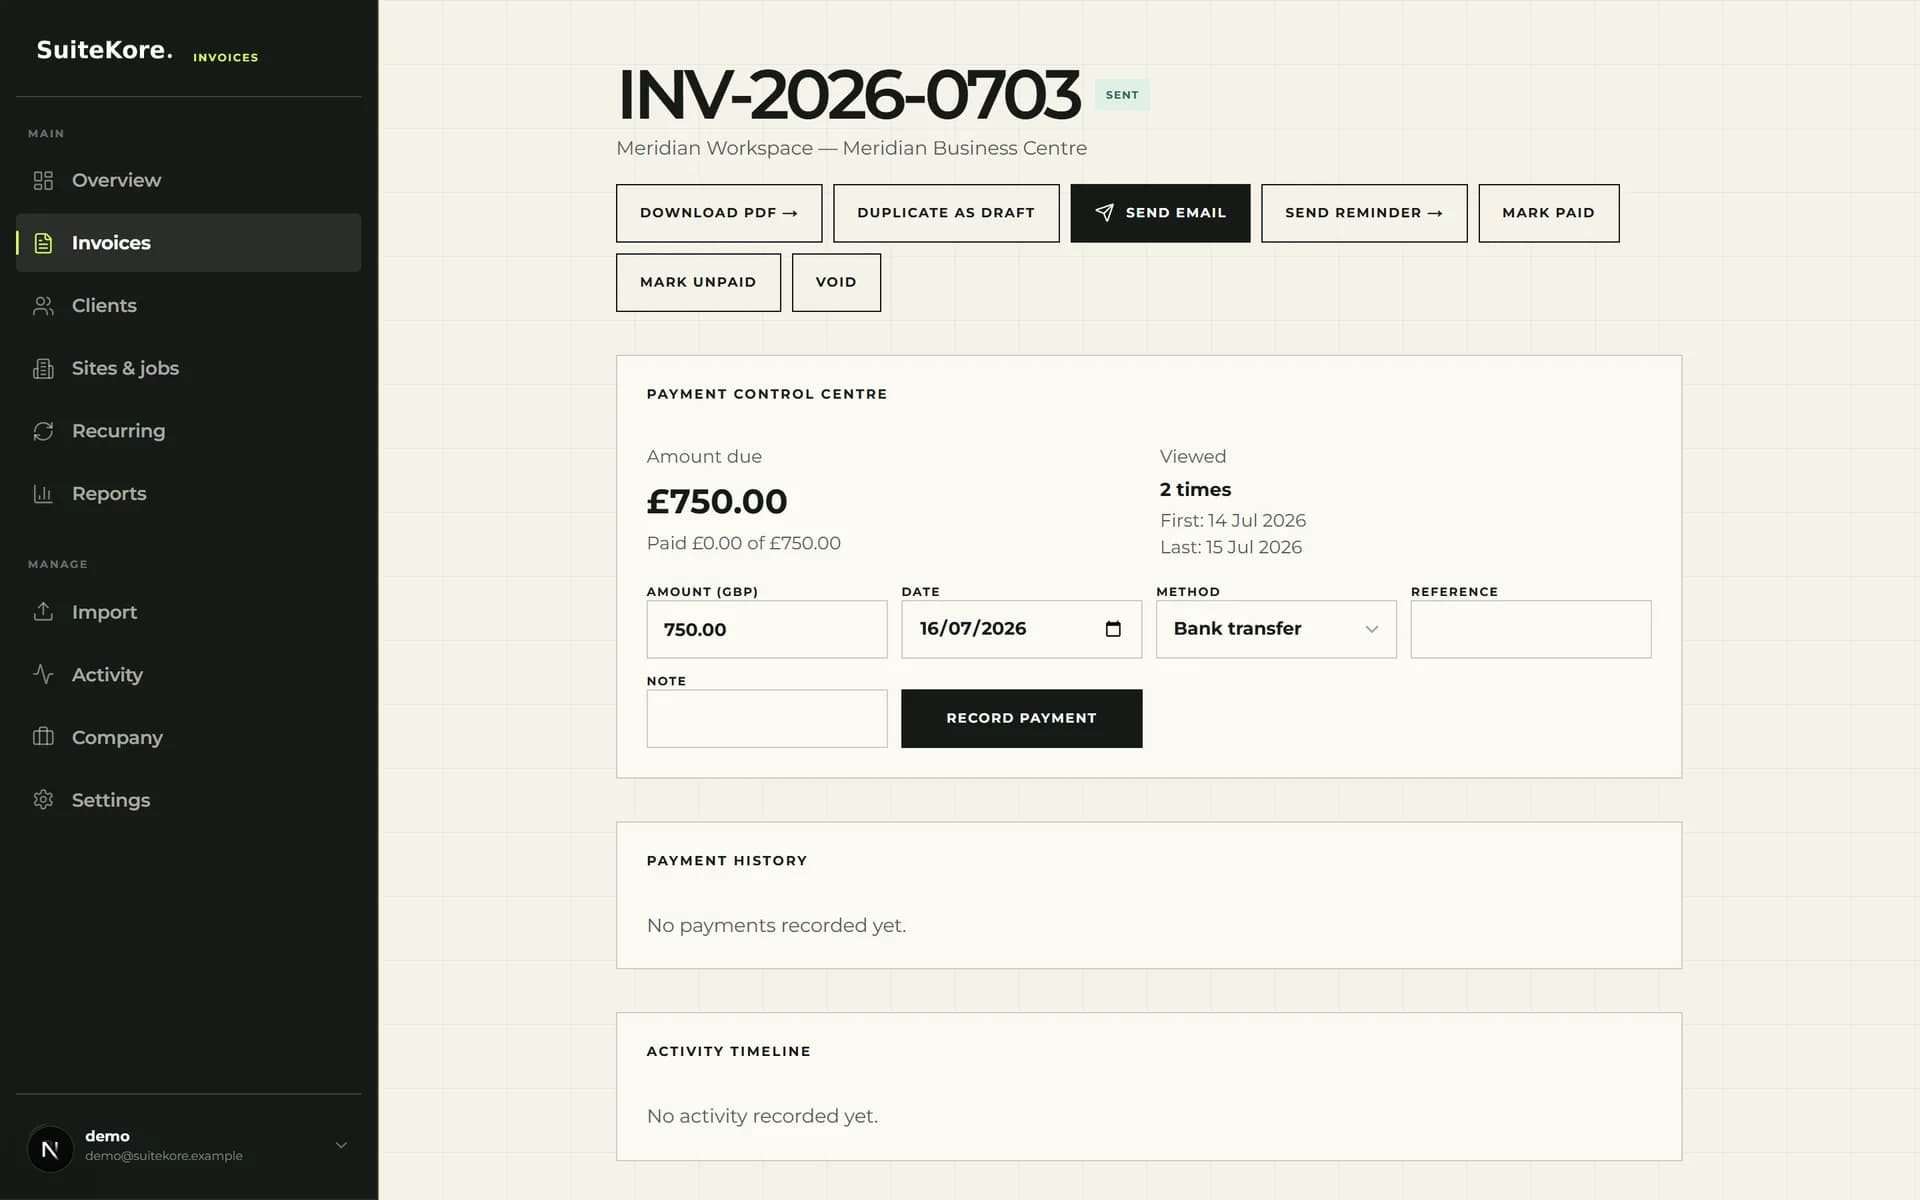
- Visible status: drafted, sent, overdue, paid, without opening the document
- Recurring schedules for maintenance contracts, separate from reactive work
- Saved sites distinct from billing addresses, since the place you worked and the office that pays are rarely the same
- An export your accountant will accept without retyping
Things that sound essential and usually are not, at least at first: mobile app parity, integrated payments on day one, and estimating tied to invoicing. Those matter at scale. Being unable to split labour from materials matters on your next invoice.
Where Suitekore fits, and where it does not
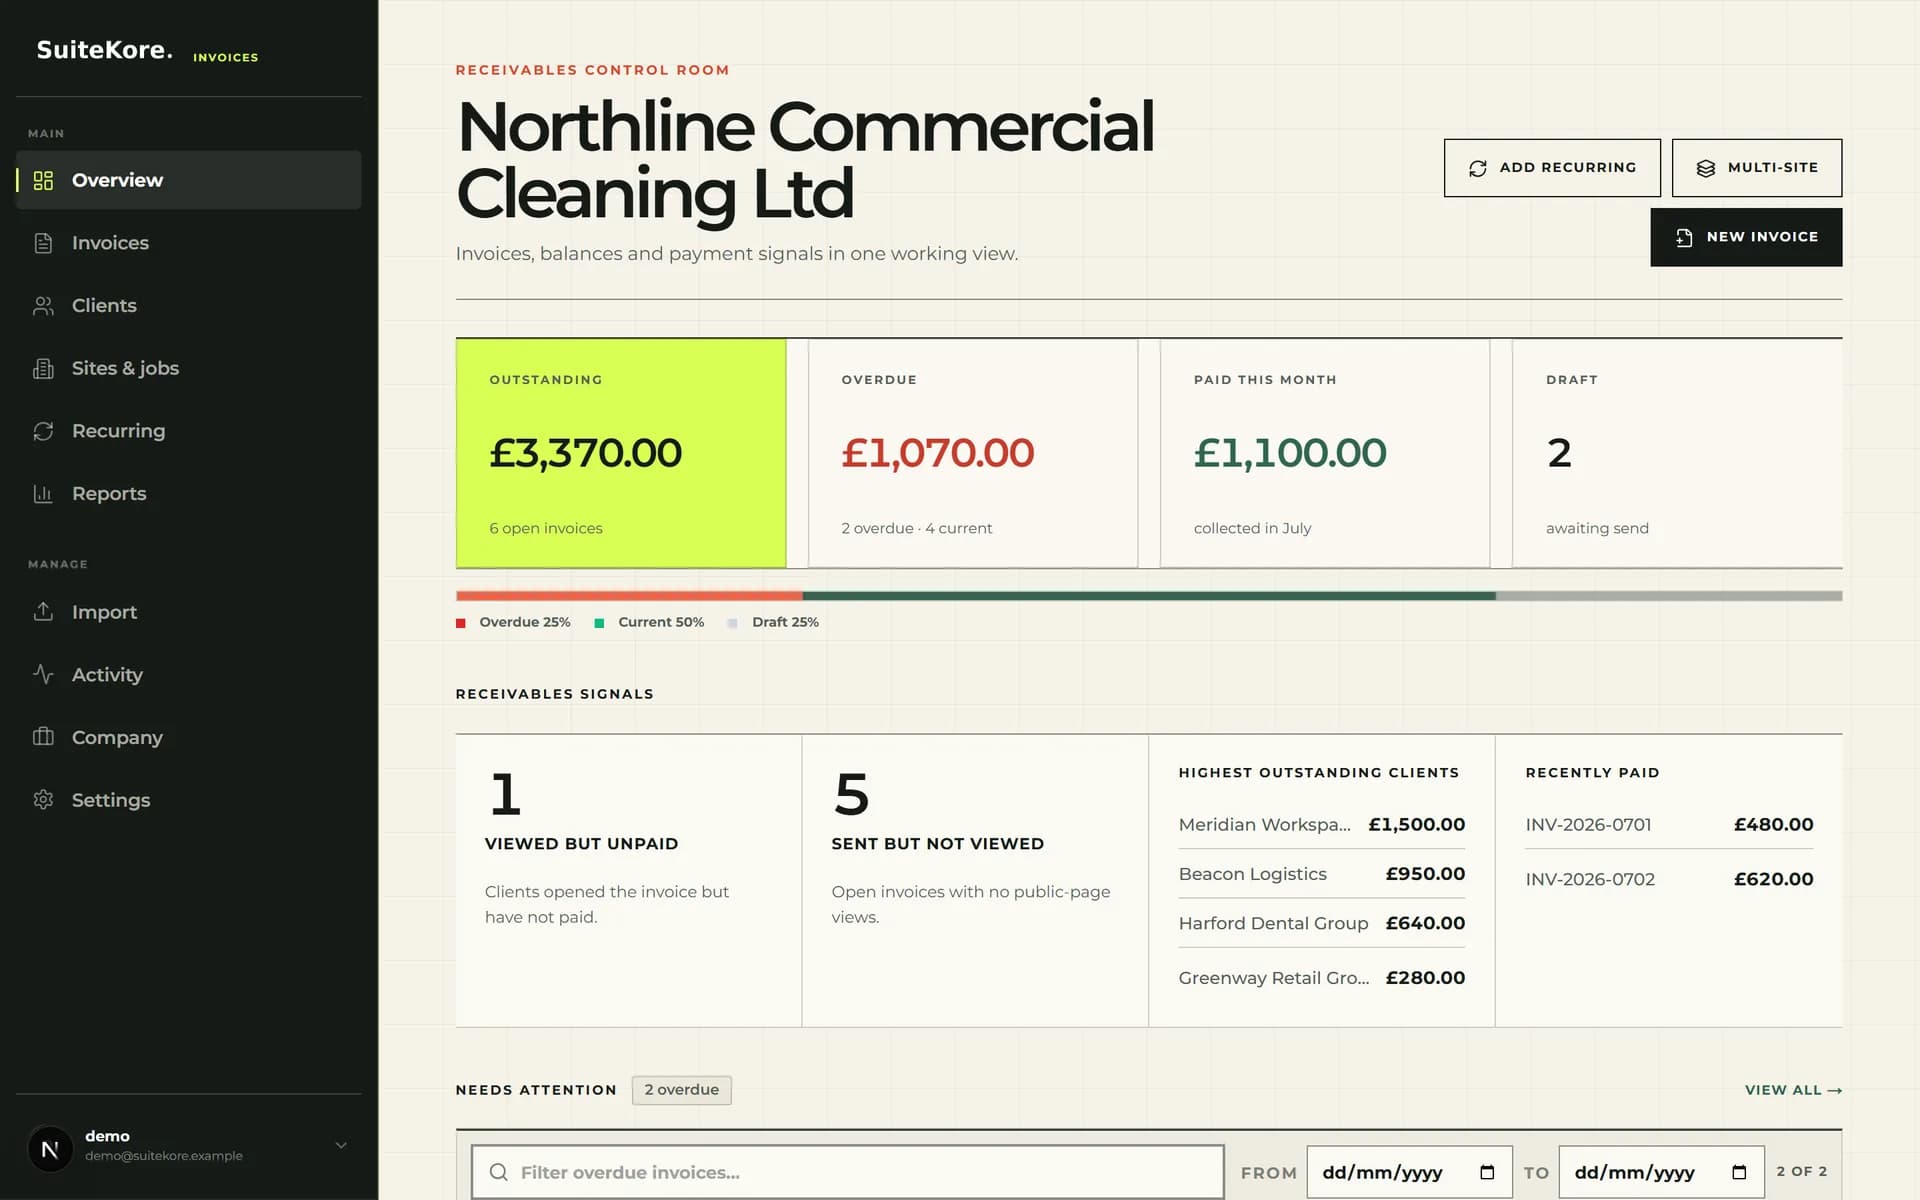
Suitekore Invoices is invoicing software, not a field service platform. It is built around saved clients and sites, line-level invoices, recurring schedules, branded PDFs, reminders and payment tracking. For an electrical business whose problem is getting accurate invoices out and knowing what is unpaid, that is the whole job.
It does not do the following, and you should price these separately if you need them:
- Issuing or storing electrical certificates and EICRs
- Engineer scheduling, dispatch and route planning
- Van stock and materials inventory
- Payroll, CIS returns or VAT submission to HMRC
- Estimating and takeoff
If you need certification and scheduling in one system, you are looking at a field service platform and the price reflects it. If you already have certification handled and the actual bottleneck is invoicing, the smaller tool is the faster change. You can try the free invoice generator without an account to see how the line structure works, or watch the product demonstration.
A weekly routine that keeps it current
None of this works as a monthly catch-up, because the detail you need is the detail you forget first: which variation was authorised, by whom, and what was agreed.
- Raise invoices weekly against completed jobs, while the variation conversations are still recent
- Split labour and materials as you enter them, rather than reconstructing the split when a contractor queries it
- Attach certificate and quote references at the point of invoicing
- Check the overdue list in the same sitting and send reminders, so chasing is a routine rather than a confrontation
- Record payments and deductions as they land, so CIS statements reconcile through the year rather than in a single April evening
Half an hour a week beats a lost afternoon a month, and it is the difference between knowing what you are owed and guessing.
Common questions
Does an electrician have to split labour and materials on an invoice?
If you are working as a subcontractor under the Construction Industry Scheme, yes, in practice. CIS deductions are taken from the labour element of your invoice, not from materials. If the invoice shows one combined figure, the contractor has nothing to work from and may deduct across the whole amount, leaving you to reclaim the difference later. Showing labour, materials and any plant hire on separate lines removes the ambiguity.
What does the VAT domestic reverse charge mean on an electrician invoice?
For construction services between two VAT-registered, CIS-registered businesses where the customer is not an end user, the customer accounts for the VAT to HMRC rather than paying it to you. Your invoice shows the work and states that the reverse charge applies, along with the VAT rate or amount the customer must account for, but does not add VAT to the total. Work for a domestic householder, or for a customer who has confirmed in writing that they are an end user, is invoiced normally with VAT charged as usual.
Should the certificate number go on the invoice?
It is not a legal requirement, but it settles arguments. Quoting the Electrical Installation Certificate, Minor Works Certificate or EICR reference alongside the work it relates to ties the invoice to the tested job. For landlords and managing agents it is often the thing their accounts team is looking for before they release payment, because it is how they evidence compliance.
Do I need job management software or just invoicing?
They solve different problems. If your difficulty is producing invoices, splitting labour and materials, and knowing what is unpaid, invoicing software is the smaller and faster thing to adopt. If you are scheduling several engineers a day, issuing certificates from the same system and managing van stock, you are looking at a field service platform and should price that separately. Buying the larger system to solve the smaller problem is the common and expensive mistake.
How should retention be shown on a commercial electrical invoice?
Show the full value of the work, then retention as a separate deduction line with the percentage stated, so the gross figure and the amount now payable are both visible. Keeping retention as a visible deduction rather than quietly reducing the invoice total is what makes it possible to invoice for its release later, which is when most retention is lost in practice.